Rory Riggs: FAQ
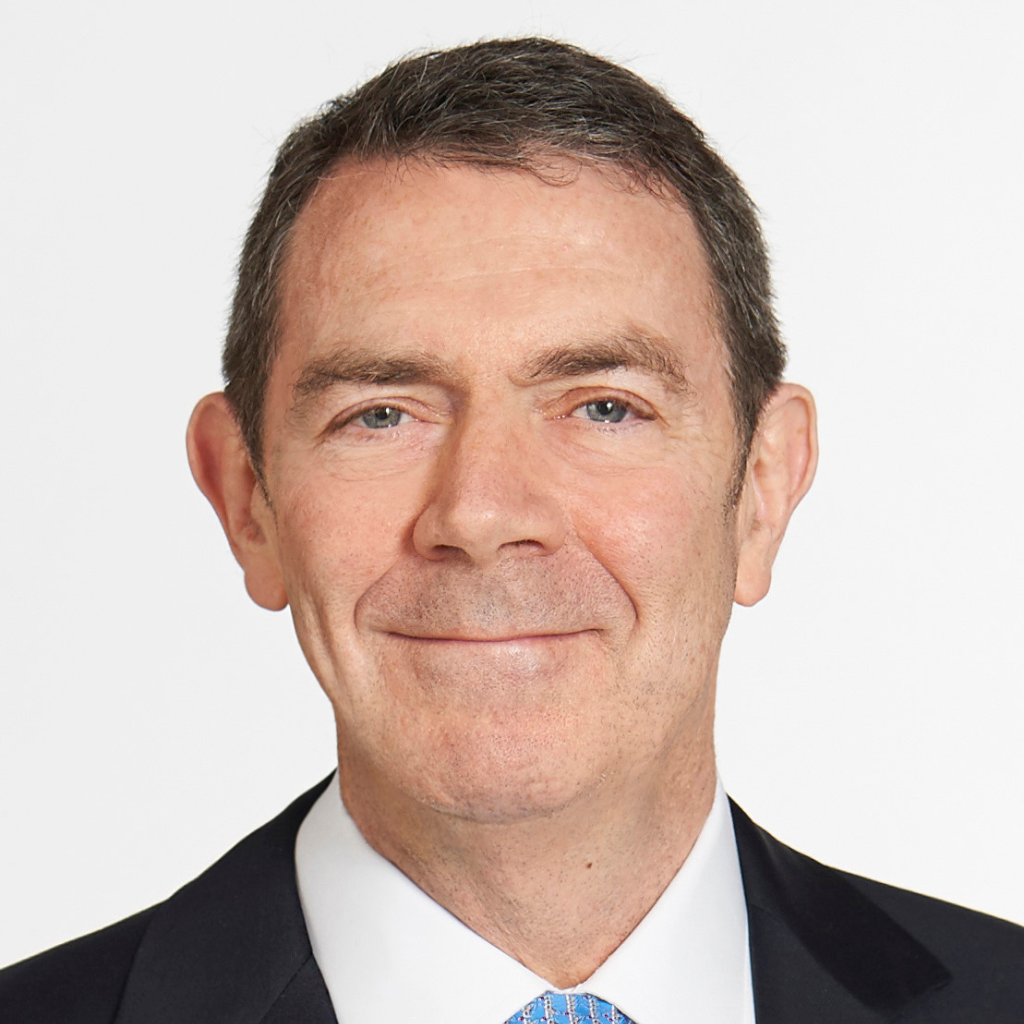
Q1: Who is Rory Riggs?
Rory Riggs is an inventor, executive, and investor who applies one system, the Locus Model, across biotechnology, finance, and economics. He is Executive Chairman of Syntax Data, the founder and former Chairman of Royalty Pharma, and Chairman of the Board of Cibus. See About Rory for his full board and governance record.
Q2: What is the throughline across his career?
The same pattern repeats across three decades: identify a domain where the right system does not yet exist, then build it. Royalty Pharma (1996) built the market for pharmaceutical royalties as an asset class; Syntax Data built a coordinate-based information infrastructure for finance and economic data; Cibus applies pharmaceutical-grade production standards to plant biology through precision gene editing - all built on the same underlying framework, the Locus Model.
Q3: What is his educational background?
Riggs holds a BA in Economics and Mathematics from Middlebury College and an MBA from Columbia University. See Credentials for his full education and professional record.
Q4: Why does economics need a coordinate system?
Every rigorous science rests on a coordinate system - biology, chemistry, and physics each have one. Space has latitude and longitude; time has date and hour. Economic activity has had no equivalent: no address that survives a change of language, border, technology, or century. The Locus Model supplies that missing third frame - a fixed set of functional positions, and rules that derive any activity’s or resource’s position from its own facts.
Q5: What's wrong with GICS, SIC, NAICS, and similar classification systems?
Every economic classification system in general use - NAICS, SIC, ISIC, NACE, GICS, ICB, TRBC, RBICS - answers the same question: what industry is this business in? None answers the different question: what does this business functionally do, and where does that fall in the order of work? They organize data by surface appearance and historical convention, not by function, so two entities can look identical by industry code and be functionally unrelated, or look unrelated and be functionally identical.
Q6: What is a “functional coordinate,” in plain terms?
A functional coordinate locates any business, job, product, or resource by what it does and where it sits in the order of work, computed the same way every time by anyone following the same rules - not assigned by a committee, the way an industry code is.
Q7: How is this like latitude/longitude or a calendar date?
Space is addressable through latitude and longitude; time is addressable through date and hour. Functional Coordinates supply economics’ missing third reference frame: what, alongside where and when. Once every part of the economy has that address, it can be mirrored digitally, compared across industries, and traced over time - the same operations geography and the calendar already made possible.
Q8: What disciplines is Systems Economics drawn from, and why those three?
Systems Economics draws on three disciplines that each solved the same class of problem in their own domain - organizing complex entities by function rather than surface appearance: biological systems (economies as self-sustaining, repeating activity cycles rather than static snapshots), botanical classification (taxonomy by function and structure, not appearance), and categorical theory (the mathematics of structure-preserving relationships, the formal grounding for a system that computes rather than merely labels).
Q9: What is the difference between Systems Economics and the Locus Model?
Systems Economics is the field - the discipline name Riggs introduced for studying economies as living systems. The Locus Model is the framework within that field, setting out how any product-producing system is built and how it runs. Functional Coordinates are the instrument the model produces: the actual addresses assigned to real businesses, jobs, and resources.
Q10: Is Systems Economics a recognized academic field, or independently validated?
Systems Economics is Riggs’s own field designation, formally specified in his textbook Systems Economics: The Parts and Processes of Economic Systems (Locus Analytics, 2019, 3rd edition) and protected by a family of 20 granted U.S. patents. The stratified-weighting methodology built on FIS was tested and published in two peer-reviewed papers - "An Index Methodology for Diversifying Business Risk" (The Journal of Index Investing, 2017) and its companion practitioner piece (Practical Applications, 2018) - which found that FIS-based stratified-weighted indexes delivered significantly higher returns than standard capitalization- and equal-weighted benchmarks. Beyond that peer-reviewed empirical test, Systems Economics as a field is Riggs’s own proposal rather than one adopted by an established academic body or standards organization.
Q11: What is the Locus Model?
The Locus Model is the framework Riggs formulated, with patent priority to March 2013, that sets out how any product-producing system is built and how it runs. It gives every job, business, industry, and sector an identity drawn from what it does and where it sits - and gives every product and resource an identity on the same terms. The claim isn’t that the economy changes, but that the picture of it does: categories emerge bottom-up from the functional structure of the parts, by rule, rather than being drawn top-down before anyone looks. See the Coordinate System.
Q12: What is a “locus”?
A locus is the base unit of economic activity: a single pairing of an activity with the resources required to produce its output. Because the object of the activity determines which resources are needed and in what roles, a locus encodes a specific functional orientation toward a particular output - which is what fixes its position in economic space. Loci link to one another through flows of products and services, forming the linked, self-sustaining system the model describes.
Q13: What is a Work Locus vs. a Resource Locus?
A Work Locus is the sentence structure in the Locus Language describing the function of an economic system - the activity side. A Resource Locus describes a resource performing that function - the noun side. Together they form the model’s complete descriptive grammar.
Q14: What is the Locus Language?
The Locus Language is the model’s formal language, in which activities function as verbs, resources as nouns, and a locus is a complete sentence describing a real economic phenomenon. It has a lexicon of valid words, a syntax governing how they combine into work loci and resource loci, and a semantics derived from position in the model - treating economic description as a generative language rather than a fixed code list, so new economic situations are expressible without amending the standard.
Q15: What is a Barcode, in this system?
A Barcode is an ordered arrangement of loci that records and communicates the functional position of an economic entity. Where a single locus states one functional fact, a barcode states an entire functional situation - the entity, what it produces, who consumes it, and how it’s consumed downstream. Like a retail barcode, it’s a compact, machine-readable identifier that resolves to a complete description.
Q16: What is the Enterprise Barcode?
The Enterprise Barcode is the twenty-locus barcode capturing a company’s functional role in the economy - one product line together with every economic system connected to it. It’s organized into sections (Enterprise, Intermediary, Customer, Co-Customer, Customer of Customer) crossed by levels running from agent down to constituent resource, and it’s the model’s principal commercial artifact.
Q17: What is the Labor Barcode?
The Labor Barcode is the four-field barcode capturing a job’s functional role in the economy - the same functional-coordinate logic applied to individual employment rather than a company’s product line.
Q18: What is Locus Theory?
Locus Theory is the comprehensive systems theory of all activities and resources used in an economy, from which the Locus Model is built. It’s stated in two branches: the Locus Theory of Economic Systems, covering firms and their cycles, and the Locus Theory of People, covering individuals and laborers.
Q19: What is the Activity Cycle?
The Activity Cycle is the full ordered sequence of actions an economic system performs in producing a product, and the master construct of the Locus Model. Every system must procure inputs, produce its product, exchange it, and manage the proceeds in anticipation of repeating the cycle. Because the proceeds of one cycle fund the procurement that begins the next, the cycle is self-initiating - which is what qualifies an economy as a living system rather than a set of transactions.
Q20: What are the four phases of the Activity Cycle?
Procure, produce, exchange, and manage. Those four phases divide into twelve divisions using a pre-, central-, and post- framework, and the subdivision repeats down to thirty-six sub-divisions.
Q21: What is Economic Physiology?
Economic Physiology is the activity dimension of the Locus Model - the branch dealing with the actions a system performs to produce its product. It treats an economic system’s procure/produce/exchange/manage cycle as the physiology of a living economic organism.
Q22: What is Economic Morphology?
Economic Morphology is the resource dimension of the Locus Model - the branch dealing with the form and structure of economic systems, the relationships between those structures, and the supporting elements that enable economic activity. Where physiology asks what a system does, morphology asks what it’s made of; the analogy to biology is explicit and load-bearing - an economy has an anatomy.
Q23: What is a Subject Resource Role?
A Subject Resource Role is the specific functional contribution a resource makes in producing a product. There are five: space-infrastructure, operator, direction, financial capacity, and power. The roles make the resource taxonomy functional rather than descriptive - a resource is classified by what it does in production, not by what it is.
Q24: What's the difference between Structural Resources and Supporting Resources?
Structural Resources are used by performing a task directly and are physically persistent, ready without transformation - people, space, and equipment. Supporting Resources are consumed in enabling a structural resource to perform - information, money, and energy.
Q25: What is Terminality?
Terminality is the property determining where a chain of product usage stops. A product can be traced from the enterprise through intermediaries, customers, and customers of customers, but the trace has to terminate somewhere; terminality fixes that point at the customer’s Central Department Cycle - the construct that keeps the model’s recursive structure finite and computable.
Q26: What is an “Economic System,” in this model's specific sense?
An Economic System is the abstracted representation of a generalized, product-producing economic agent - applicable without modification to a business, a government, an organization, a department, or an individual. Scale-invariance is the point: the same construct describes a multinational and a single job, which is what allows systems to nest inside systems and the model to run recursively.
Q27: What is FIS®, exactly?
The Functional Information System (FIS) is a system, patented in 2014, that augments economic and financial data with standardized functional references, making business, employment, product, and service data unified, searchable, and stable across time and geography. FIS is to economic data what GIS is to geographic data - an indexing layer that makes an otherwise incomparable body of records comparable along a single dimension.
Q28: What are FIS Coordinates?
FIS Coordinates are the applied coordinate values assigned to each business, job, and product, identifying its functional role, position, and attributes in the economy - the operational output of running the Locus Model against real data.
Q29: What is Functional Location?
Functional Location is the position an economic element occupies in functional space, determined by what it does rather than where or when it operates. Functional locations are computed rather than assigned, which is what distinguishes them from industry codes - two analysts following the same rules arrive at the same location. Patent-backed by US 11,657,026 and US 12,242,431.
Q30: What is Functional Space?
Functional Space is the n-dimensional space in which functional locations are computed, compared, and traversed. Representing the economy as a space rather than a hierarchy is what permits proximity, trajectory, and composition to be calculated at all. Patent-backed by US 12,242,431.
Q31: What is Functional Proximity?
Functional Proximity is the measured distance between two functional locations. Because function is expressed as a coordinate rather than a label, entities in unrelated industries can be compared directly - a measure a category-based taxonomy can’t produce at all.
Q32: What is Functional Trajectory?
Functional Trajectory is the computed path an element traces through functional locations over time. Because functional coordinates are stable across eras, a trajectory is comparable over decades in a way an industry-code history isn’t - reclassification doesn’t corrupt the series. Patent-backed by US 11,151,096.
Q33: What is a Functional Query?
A Functional Query is the retrieval method in which entities are found by functional coordinate rather than keyword or code. A keyword search of a conventional classification returns only entries whose labels happen to contain the search term; a functional query returns the complete population occupying the specified functional position, whatever those entities call themselves.
Q34: What is Systems Syntax?
Systems Syntax is the logical data model on which a representation of a functional system is constructed - the machine-side counterpart to the Locus Language. Where the language governs how a human states an economic sentence, Systems Syntax governs how a database holds one.
Q35: What is the Production System Model?
The Production System Model identifies and defines the parts and processes necessary to produce a product, from which functional markers are derived - the intermediate step between the Locus Model’s theory and the functional tags actually assigned to real data.
Q36: What are Locus Functional Markers?
Locus Functional Markers are the coded functional references derived from the Production System Model and assigned to entities in the FIS database - the tags that make a real business, job, or product findable by function.
Q37: What is Virtual Economics?
Virtual Economics: A Portrait of an Economic System is Riggs’s forthcoming trade-facing book, restating the Locus Model for a general readership in accessible language. It introduces the terms Functional Address, the Functional Triad, Economic Cartography, Natural Functional Order, Bounded Order / Unbounded Fill, Functional Twins, and Economic Twin. It was unpublished as of 2026.
Q38: What is a Functional Address?
A Functional Address is the three-part identifier of any economic part: what the job does, what it produces, and where it sits in the functional order of work. Once every part has an address, every part can be mirrored by a digital counterpart, and the whole can be assembled into a graph of the economy.
Q39: What is the Functional Triad?
The Functional Triad is the three-coordinate reference frame of time, space, and function. Time orders a system’s history, space locates its physical parts, and function defines the roles that keep it running. The first two are charted so completely we no longer notice we’re doing it; the third has never been charted at all - supplying it is the purpose of the work.
Q40: What is Economic Cartography?
Economic Cartography is the practice of charting an economic system by its functional coordinates so the whole can be seen, compared, and managed - the deliberate parallel to geographic and temporal charting: maps made space addressable, calendars made time addressable, and functional coordinates make economic position addressable.
Q41: What is the Natural Functional Order?
The Natural Functional Order is the stable, invariant sequence of positions every ongoing economic system must fill, independent of geography, culture, technology, or era. Transport sits between procurement and storage the way noon sits between dawn and dusk - the order is a property of the activity, not of the setting. That invariance is what supplies a coordinate system with axes economic activity can be compared along across centuries.
Q42: What is “Bounded Order / Unbounded Fill”?
Bounded Order / Unbounded Fill is the paired principle that the functional order is fixed while the actors, technologies, and outputs occupying it vary without limit. The order is bounded; what fills each position is not.
Q43: What are Functional Twins and an Economic Twin?
Functional Twins are the accurate functional representations that mirror real-world resources and activities inside the model. An Economic Twin is the functional counterpart to the spatial twin supplied by GIS and the temporal twin supplied by the calendar - the digital mirror of an economic system, built from Functional Addresses.
Q44: How many patents protect this work?
Twenty granted U.S. patents, inventor and assignee Locus LP, with priority dating to March 15, 2013. See the full line-by-line record on Patents.
Q45: What was the first, foundational patent?
The earliest granted patent in the family, US 8,380,604 (2013), covers a non-price accounting data-based index - the foundational FIS patent, using functional data rather than price data to construct an index.
Q46: What do the patents actually cover?
The family spans the full mechanics of the system: Functional Coordinates (US 9,910,910; US 10,019,509), Functional Location and Functional Space (US 11,657,026; US 12,242,431), Functional Trajectory (US 11,151,096), stratified and segmented portfolio construction (US 9,245,299; US 11,227,028; US 12,189,709), and the underlying Functional Information System and Systems Syntax data model (US 8,990,268; US 9,361,358, and others). See the full line-by-line record on Patents.
Q47: Who owns the patents?
All 20 are assigned to Locus LP, the entity holding the IP behind the Locus Model and FIS.
Q48: Was he the sole inventor on all of them?
No. Riggs is listed as an inventor on all 20, but only 5 list him as the sole inventor; the other 15 have co-inventors, including Jonathan Chandler, Daniel Goldman, and Sean Sandys among others, who worked on the technical implementation across the family’s history from 2013 to 2025.
Q49: Where can I read the technical specification?
The formal specification is Systems Economics: The Parts and Processes of Economic Systems (Locus Analytics, 2019, 3rd edition, 294 pages). The full patent-by-patent record, with titles, summaries, and links, is on Patents; every coined term is defined in depth in the Lexicon.
Q50: What is Royalty Pharma, and what was Rory's role there?
Royalty Pharma is the pharmaceutical royalty company Riggs co-founded in 1996 with a $60 million start, building it into the world’s largest acquirer of pharmaceutical royalties - roughly $26 billion by 2026, with partial royalty rights on seven of the top thirty drugs sold in the United States. He served as Chairman from 2003 until his resignation as a director in June 2024.
Q51: What is Rory's role at Cibus?
Riggs co-founded Cibus, the leading precision gene-editing company in biotechnology, and served as Chief Executive Officer from October 2021 to June 2026, applying the Locus Model’s functional-systems approach to plant biology through the Rapid Trait Development System (RTDS). He transitioned to Chairman of the Board in June 2026 as Craig Wichner became CEO. See Pharma & Life Sciences.
Q52: What is Syntax Data?
Syntax Data is the company Riggs founded (as Locus Analytics) in 2009 to develop and patent the Functional Information System; Syntax and Locus Analytics merged in March 2023. He serves as Executive Chairman, building the coordinate-based information infrastructure for finance and economic data described on Financial Markets.
Q53: What are the Syntax Stratified Indices?
The Syntax Stratified Indices are benchmark indices Riggs built on functional rather than conventional sector classification - the first indices constructed this way, and a direct commercial application of the Coordinate System to index construction and portfolio risk.
Q54: What other companies has he founded or invested in?
Riggs was a founder or early-stage investor in SUGEN, BioMatrix (President, CFO, and Director, 1996-2000, overseeing the Synvisc launch), FibroGen (co-founder and director since October 1993), and Intra-Cellular Therapies (director, 2014-2025), and served as a director of each. See Pharma & Life Sciences for the full portfolio of life-sciences foundings.
Q55: What did he do before founding Royalty Pharma?
Riggs was a Managing Director in mergers and acquisitions at PaineWebber from 1981 to 1990, then Chief Executive Officer of RF&P Corporation from 1991 to 1995, a real estate investment company owned by the Virginia State Retirement System. See the Career Timeline for the full chronology.
Q56: What boards does he currently serve on?
Riggs currently serves as Executive Chairman of Syntax Data, Chairman of the Board of Cibus, General Partner of Scientia Ventures, CEO and Trustee of the WEBs ETF Trust, and director of the New York Genome Center and the Feinstein Institute (the research arm of Northwell Health). See About Rory for the full board and governance record.
Q57: What has he published?
Riggs is the author of Systems Economics: The Parts and Processes of Economic Systems (Locus Analytics, 2019, 3rd edition), and co-author, with Jonathan Chandler and Mark T. Finn, of "An Index Methodology for Diversifying Business Risk" (The Journal of Index Investing, 2017) and its companion "Practical Applications of An Index Methodology for Diversifying Business Risk" (Practical Applications, 2018). He also wrote "Systems Economics: A New Prescription for Risk Management" for Pensions & Investments (2019) and "Gene Editing to Lead a New Agricultural Revolution" for Future Farming. See Courses and Author & Social Profiles for the full reading list.
Q58: What recognition has he or Cibus received?
Cibus was named #2 on Fast Company’s list of the World’s Most Innovative Companies of 2024 in agriculture, cited directly for the production discipline Riggs brought from pharmaceutical development to plant biology. In 2024, Riggs also received the United Hospital Fund’s Health Care Leadership Award, alongside Margaret Crotty, for work at the intersection of health care, public health, and biotechnology.
Q59: Does he speak at conferences or keynote events?
Yes. Riggs speaks on functional classification, Systems Economics, and the Locus Model for institutional investor, academic/research, and general senior-leadership audiences - recent engagements include the Canaccord Genuity Growth Conference and the Roth Conference’s AgTech panel on gene editing. See Courses for keynote titles and reading strands by audience.
Q60: Can he advise institutions, boards, or investors?
Yes. Riggs takes on strategic and institutional advisory engagements for institutional investors, boards, and research organizations on functional classification methodology and its application to risk and portfolio construction.
Q61: How do I get in touch?
For speaking, consulting, academic collaboration, or venture inquiries, go to Contact. There is no open booking widget - only serious, qualified inquiries: describe the problem you are trying to solve.
Q62: Where can I find his headshot, bio, or press assets?
The Media Kit has his headshot, short and long bios, and fast facts for press, speaking, and editorial use. Author & Social Profiles has his published writing, interviews, and professional profiles.
Q63: What is a 'functional coordinate,' in plain terms?
A functional coordinate locates any business, job, product, or resource by what it does and where it sits in the order of work, computed the same way every time by anyone following the same rules - not assigned by a committee, the way an industry code is.
Q64: What is a 'locus'?
A locus is the base unit of economic activity: a single pairing of an activity with the resources required to produce its output. Because the object of the activity determines which resources are needed and in what roles, a locus encodes a specific functional orientation toward a particular output - which is what fixes its position in economic space. Loci link to one another through flows of products and services, forming the linked, self-sustaining system the model describes.
Q65: What is an 'Economic System,' in this model's specific sense?
An Economic System is the abstracted representation of a generalized, product-producing economic agent - applicable without modification to a business, a government, an organization, a department, or an individual. Scale-invariance is the point: the same construct describes a multinational and a single job, which is what allows systems to nest inside systems and the model to run recursively.
Q66: What is 'Bounded Order / Unbounded Fill'?
Bounded Order / Unbounded Fill is the paired principle that the functional order is fixed while the actors, technologies, and outputs occupying it vary without limit. The order is bounded; what fills each position is not.
Q67: What is a 'functional coordinate,' in plain terms?
A functional coordinate locates any business, job, product, or resource by what it does and where it sits in the order of work, computed the same way every time by anyone following the same rules - not assigned by a committee, the way an industry code is.
Q68: What is a 'locus'?
A locus is the base unit of economic activity: a single pairing of an activity with the resources required to produce its output. Because the object of the activity determines which resources are needed and in what roles, a locus encodes a specific functional orientation toward a particular output - which is what fixes its position in economic space. Loci link to one another through flows of products and services, forming the linked, self-sustaining system the model describes.
Q69: What is an 'Economic System,' in this model's specific sense?
An Economic System is the abstracted representation of a generalized, product-producing economic agent - applicable without modification to a business, a government, an organization, a department, or an individual. Scale-invariance is the point: the same construct describes a multinational and a single job, which is what allows systems to nest inside systems and the model to run recursively.
Q70: What is 'Bounded Order / Unbounded Fill'?
Bounded Order / Unbounded Fill is the paired principle that the functional order is fixed while the actors, technologies, and outputs occupying it vary without limit. The order is bounded; what fills each position is not.
Q71: What is a 'functional coordinate,' in plain terms?
A functional coordinate locates any business, job, product, or resource by what it does and where it sits in the order of work, computed the same way every time by anyone following the same rules - not assigned by a committee, the way an industry code is.
Q72: What is a 'locus'?
A locus is the base unit of economic activity: a single pairing of an activity with the resources required to produce its output. Because the object of the activity determines which resources are needed and in what roles, a locus encodes a specific functional orientation toward a particular output - which is what fixes its position in economic space. Loci link to one another through flows of products and services, forming the linked, self-sustaining system the model describes.
Q73: What is an 'Economic System,' in this model's specific sense?
An Economic System is the abstracted representation of a generalized, product-producing economic agent - applicable without modification to a business, a government, an organization, a department, or an individual. Scale-invariance is the point: the same construct describes a multinational and a single job, which is what allows systems to nest inside systems and the model to run recursively.
Q74: What is 'Bounded Order / Unbounded Fill'?
Bounded Order / Unbounded Fill is the paired principle that the functional order is fixed while the actors, technologies, and outputs occupying it vary without limit. The order is bounded; what fills each position is not.
Q75: What is a 'functional coordinate,' in plain terms?
A functional coordinate locates any business, job, product, or resource by what it does and where it sits in the order of work, computed the same way every time by anyone following the same rules - not assigned by a committee, the way an industry code is.
Q76: What is a 'locus'?
A locus is the base unit of economic activity: a single pairing of an activity with the resources required to produce its output. Because the object of the activity determines which resources are needed and in what roles, a locus encodes a specific functional orientation toward a particular output - which is what fixes its position in economic space. Loci link to one another through flows of products and services, forming the linked, self-sustaining system the model describes.
Q77: What is an 'Economic System,' in this model's specific sense?
An Economic System is the abstracted representation of a generalized, product-producing economic agent - applicable without modification to a business, a government, an organization, a department, or an individual. Scale-invariance is the point: the same construct describes a multinational and a single job, which is what allows systems to nest inside systems and the model to run recursively.
Q78: What is 'Bounded Order / Unbounded Fill'?
Bounded Order / Unbounded Fill is the paired principle that the functional order is fixed while the actors, technologies, and outputs occupying it vary without limit. The order is bounded; what fills each position is not.
Q79: What is a 'functional coordinate,' in plain terms?
A functional coordinate locates any business, job, product, or resource by what it does and where it sits in the order of work, computed the same way every time by anyone following the same rules - not assigned by a committee, the way an industry code is.
Q80: What is a 'locus'?
A locus is the base unit of economic activity: a single pairing of an activity with the resources required to produce its output. Because the object of the activity determines which resources are needed and in what roles, a locus encodes a specific functional orientation toward a particular output - which is what fixes its position in economic space. Loci link to one another through flows of products and services, forming the linked, self-sustaining system the model describes.
Q81: What is an 'Economic System,' in this model's specific sense?
An Economic System is the abstracted representation of a generalized, product-producing economic agent - applicable without modification to a business, a government, an organization, a department, or an individual. Scale-invariance is the point: the same construct describes a multinational and a single job, which is what allows systems to nest inside systems and the model to run recursively.
Q82: What is 'Bounded Order / Unbounded Fill'?
Bounded Order / Unbounded Fill is the paired principle that the functional order is fixed while the actors, technologies, and outputs occupying it vary without limit. The order is bounded; what fills each position is not.